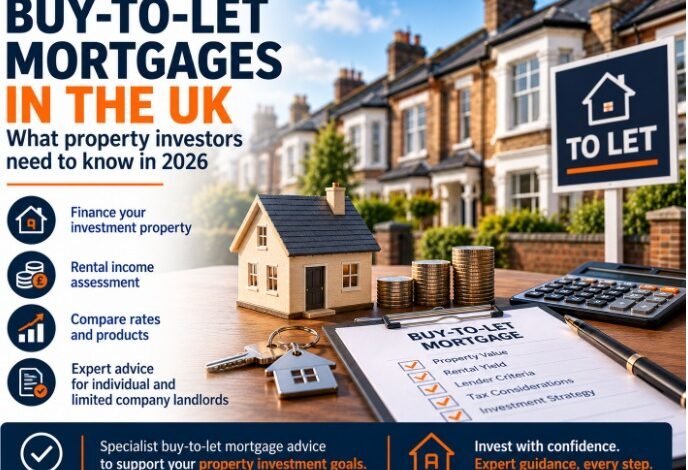
Property investment can provide rental income and the potential for long-term capital growth, but becoming a landlord involves more than purchasing a property and finding tenants. Investors need to understand mortgage criteria, taxation, maintenance costs, rental demand and the risks associated with changing interest rates.
In 2026, careful financial planning remains particularly important. Borrowing costs can change, rental income is not guaranteed and regulatory responsibilities continue throughout a property’s ownership. Anyone considering a buy-to-let investment should evaluate the full business case before committing funds.
What Is a Buy-to-Let Mortgage?
A buy-to-let mortgage is designed for purchasing or refinancing a property that will normally be rented to tenants rather than occupied as the borrower’s main home.
These mortgages are assessed differently from many standard residential mortgages. Lenders may focus on the expected rental income, the property value, the applicant’s financial position and the proposed loan-to-value ratio.
Some lenders also have minimum income, age, experience or portfolio requirements. Limited company landlords may have access to specific products, but company ownership can introduce additional legal, tax and accounting considerations.
Not every property is suitable for every mortgage product. Houses in multiple occupation, holiday lets, new-build properties and certain flats may be subject to additional lending restrictions.
How Do Lenders Assess Rental Income?
Rental income is a central part of many buy-to-let affordability assessments.
A lender may require the expected rent to exceed a specified proportion of the mortgage interest calculated at a particular assessment rate. The exact calculation varies between lenders and can depend on whether the property is owned personally or through a company, the applicant’s tax position and the type of tenancy.
For this reason, an advertised rental yield does not guarantee mortgage approval.
Suppose an investor expects a property to generate £1,200 per month in rent. That is £14,400 annually before expenses. The investor must still account for mortgage payments, repairs, insurance, periods without tenants, letting-agent fees and relevant taxes.
A property that appears profitable when only rent and mortgage interest are considered may produce a much smaller net return once all costs are included. Contact us now.
Calculate the Full Investment Return
Before making an offer, prepare a realistic cash-flow forecast.
Include the purchase price, deposit, legal fees, valuation costs, mortgage fees, any property transaction tax, furnishing, repairs and compliance costs. Then estimate ongoing expenses and allow for periods when rent may not be received.
Investors should distinguish between gross rental yield and net return. Gross yield is generally calculated by dividing annual rent by the property purchase price. Net yield attempts to account for relevant operating expenses, although the exact calculation varies.
For example, a property purchased for £200,000 that generates £12,000 in annual rent has a gross rental yield of 6%. That figure does not show the profit remaining after mortgage costs, maintenance, management, insurance, tax and vacancies.
It is also important to distinguish rental cash flow from capital growth. Property prices can fall, and selling a property may involve additional expenses and tax liabilities.
Interest Rates and Financing Choices in 2026
Buy-to-let borrowing costs are influenced by market rates, lender funding costs, deposit size, property type and borrower circumstances.
The Bank of England held Bank Rate at 3.75% at its September 2026 meeting. Nevertheless, fixed mortgage rates can change independently as wholesale funding costs and expectations move. October market reports have highlighted pressure on residential fixed-rate pricing, and buy-to-let borrowers should also check current product terms rather than assume that older rates remain available.
Investors commonly compare fixed-rate and variable-rate products. A fixed rate can provide greater certainty over the interest rate during the agreed period, while a variable product can move according to its terms.
The cheapest initial rate is not necessarily the most appropriate choice. Compare product fees, early repayment charges, overpayment conditions, rental assessment requirements and the likely cost of refinancing.
Should You Buy Through a Limited Company?
Some landlords purchase investment properties through a limited company, while others own them personally. The appropriate structure depends on individual circumstances and should not be chosen solely because one approach appears more tax-efficient.
A limited company may have different mortgage products, fees and underwriting requirements. Company ownership can also involve accounting costs, administrative responsibilities and different tax treatment.
Personal ownership and company ownership can produce different outcomes depending on the investor’s income, intended holding period, financing costs and future plans. Tax treatment may change, and the rules governing mortgage interest relief and property income are important to understand.
Speak to a qualified tax adviser or accountant before deciding. A mortgage adviser can explain available financing options, but mortgage advice is not a substitute for individual tax advice.
Understand Your Legal and Landlord Responsibilities
Landlords must comply with the requirements applicable to the property and tenancy. Depending on the circumstances and location, these may include gas safety checks, electrical safety requirements, energy performance rules, deposit protection, licensing and obligations relating to property condition.
Rules differ across England, Scotland, Wales and Northern Ireland. Requirements can also vary by local authority, property type and tenancy arrangement.
Before purchasing, research the regulations that will apply to the specific property. Budget for compliance and maintenance rather than treating these expenses as unexpected exceptions.
A letting agent may help with tenant management, but using an agent does not automatically remove the landlord’s legal responsibilities.
Plan for Voids, Repairs and Unexpected Costs
Rental income is not guaranteed. A tenant may leave, a property may need significant repairs or the local rental market may weaken.
Investors should consider maintaining a cash reserve sufficient to cover mortgage payments and essential expenses during periods without rental income. They should also test whether the investment remains viable if interest rates rise, repairs cost more than expected or rent is lower than forecast.
Insurance may help manage certain risks, but cover varies by policy. Review exclusions, excesses and the conditions for making a claim.
Avoid relying entirely on projected capital appreciation to justify an investment that produces persistently weak cash flow.
How Mortgage Advice Can Help
A mortgage adviser familiar with buy-to-let lending can help explain lender criteria, compare eligible products and identify documents needed for an application. The range of options available depends on the adviser’s market coverage and the relevant permissions.
Prestige Mortgage Solutions Ltd advertises buy-to-let mortgage services alongside residential mortgages and remortgaging. Potential customers should ask whether the adviser handles individual and limited company applications, portfolio landlords and the particular property type under consideration. It is also sensible to confirm fees, lender access and regulatory status before proceeding. Some buy-to-let lending falls outside FCA regulation, so the status of the specific transaction matters.
Final Thoughts
Buy-to-let investment requires a realistic assessment of income, expenses, financing and risk. Rental demand, mortgage terms and tax rules can all affect the final result, and a positive gross yield alone is not enough to establish whether a property is a sound investment.
Before purchasing, build a detailed cash-flow forecast, review landlord responsibilities and compare current mortgage options. Professional mortgage, legal and tax advice can help you understand the commitments involved and make a more informed decision.
This article is for general information only and does not constitute investment, mortgage, legal or tax advice. Rental income and property values are not guaranteed. Some buy-to-let mortgages are not regulated by the FCA. Always check the status of your particular transaction and obtain suitable professional advice.

